When it comes to auto insurance, Massachusetts drivers find themselves navigating a complex landscape of regulations, coverage options, and cost factors. Whether you’re a new driver or a seasoned road warrior, understanding how much is auto insurance in Massachusetts is crucial to making informed decisions that protect both your vehicle and your wallet.
In this guide, we’re diving deep into the essentials of Massachusetts auto insurance. From mandatory coverage components and cost influences to future trends and money-saving tips, you’ll get a complete picture that’s as easy to digest as a Boston cream pie. Let’s hit the road!
Understanding Auto Insurance in Massachusetts
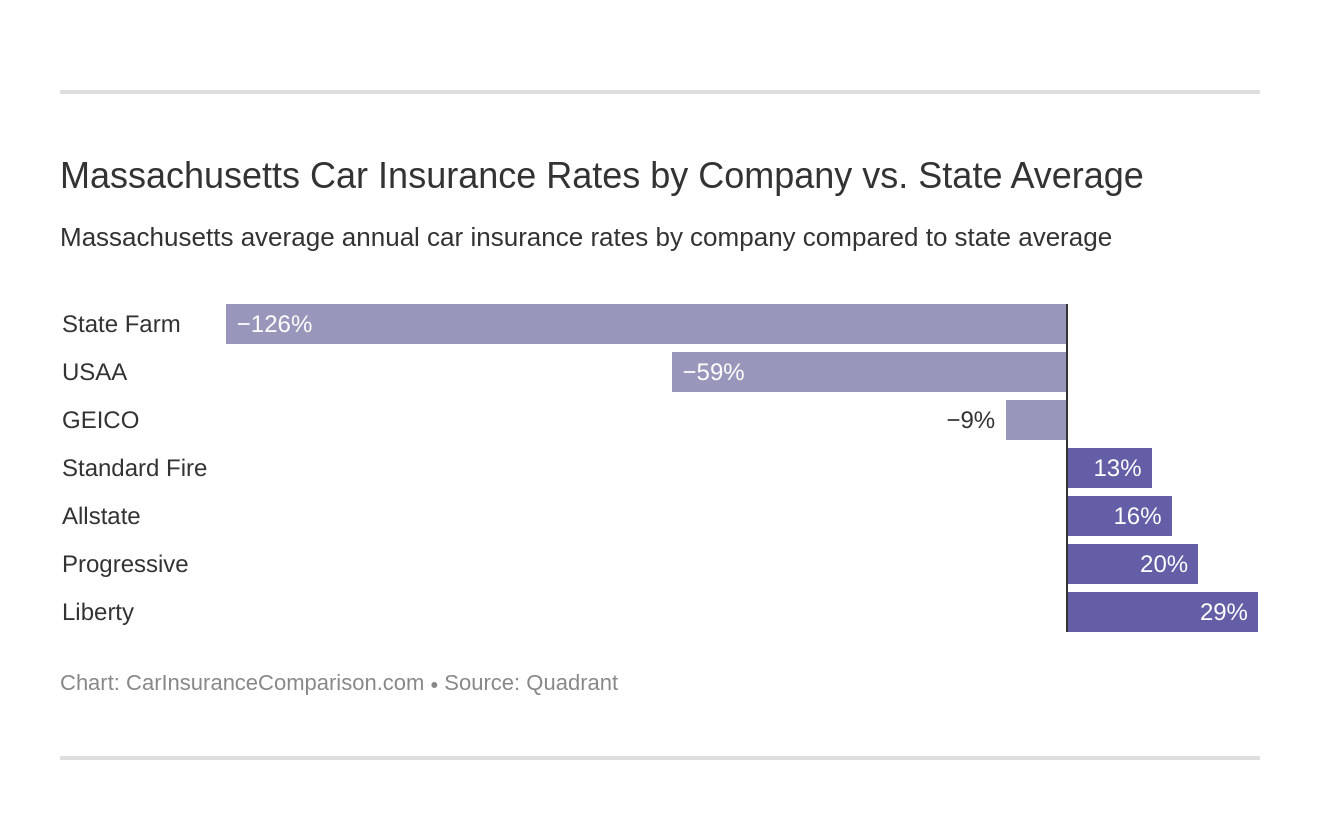
Did you know that Massachusetts has some of the strictest auto insurance laws in the U.S.? Yep, if you’re driving around the Bay State, you’ve got to know your stuff.
Whether you’re a new driver or just moved to Massachusetts, understanding the insurance requirements here is crucial. But don’t worry, I’ve got you covered.
Basic Components of Auto Insurance Coverage in Massachusetts
Let’s break it down. Auto insurance in Massachusetts consists of several key components, and here’s the deal: you can’t hit the road without them. First up, you have Bodily Injury Liability. This covers injuries you cause to someone else. Next, there’s Property Damage Liability. It takes care of damages to someone else’s property. And don’t forget Personal Injury Protection (PIP), which is mandatory for covering medical expenses.
Legal Requirements for Auto Insurance in Massachusetts
Here’s a fact that might surprise you: Massachusetts mandates specific minimum coverage limits. As a driver, you need at least $20,000 per person and $40,000 per accident for bodily injury. Property damage liability requires a minimum of $5,000. Then there’s PIP, which has to be at least $8,000. And you can’t skip out on Uninsured Motorist Coverage either. It mirrors bodily injury limits.
Common Types of Auto Insurance Policies Available in Massachusetts
There are several types of policies you might consider. Beyond the legal requirements, you can opt for Comprehensive Coverage to protect against non-collision-related damage. Or, how about Collision Coverage? It handles the repair costs if you hit another vehicle or object. For those who want extra peace of mind, there’s Underinsured Motorist Coverage, which kicks in when the other driver’s insurance isn’t enough.
Pro Tip: Always shop around and compare policies. Massachusetts has a competitive market, so leverage it to get the best deal.
Factors Affecting Auto Insurance Costs
Ever wonder why your auto insurance bill seems to fluctuate more than the New England weather? You’re not alone. Auto insurance premiums in Massachusetts can feel like a mystery. But, they’re actually impacted by a handful of key factors.
Understanding these factors can help you make smarter decisions and possibly save some cash. Let’s dive into what really drives those numbers.
Age and Driving Experience
Your age and how long you’ve been driving can have a massive impact on your premium. Younger drivers, especially those under 25, typically pay more because they’re considered higher risk. As you gain more experience on the road, your rates tend to drop. But, if you’re a seasoned driver with a few accidents under your belt, your premiums could skyrocket faster than you can say “fender bender.” Pro Tip: Consider taking a defensive driving course to keep your premium in check.
Location and Its Impact
Where you park your car overnight can be just as important as how you drive it. Insurers look closely at your ZIP code because living in an area with high crime rates or heavy traffic can mean more claims. This translates to higher premiums for you. Urban areas like Boston are generally pricier compared to suburban or rural spots in Massachusetts. Here is the deal: moving just a few miles could save you hundreds each year.
Vehicle Type and Usage
The type of car you drive and how you use it are crucial in determining your insurance costs. Insurers consider the car’s make, model, and year. High-performance cars usually have higher premiums because they’re more expensive to repair. Plus, if you use your car for business or have a long commute, expect to pay more. Why? More time on the road means a greater chance of accidents. Choose a car that’s both budget-friendly and safe to get the best rates.
Price Comparison of Auto Insurance Providers
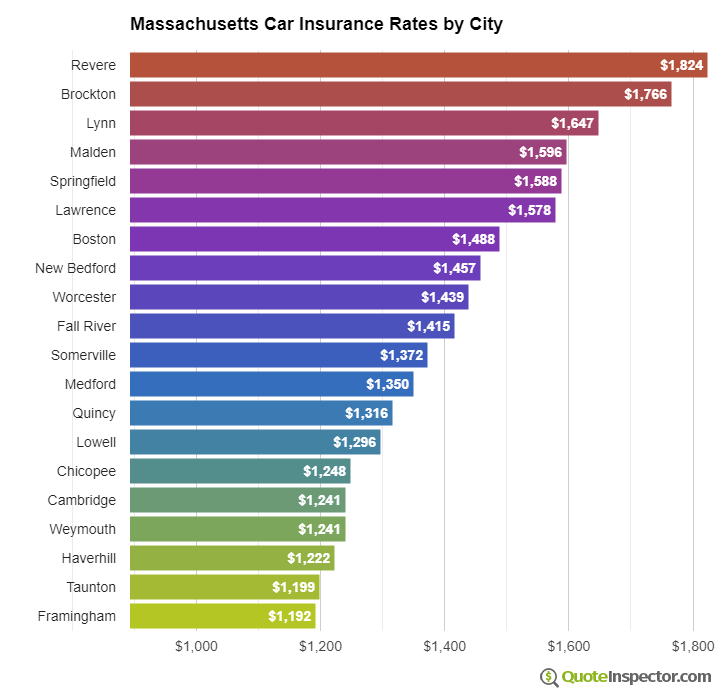
Ever wonder how much you could be overpaying for auto insurance in Massachusetts? You might be shocked to find out that prices can vary by hundreds of dollars!
To get the best deal, you need to compare prices from different providers. Knowing who offers the best rates can save you a ton of money—but only if you know where to look.
Average Costs of Auto Insurance from Various Providers
Here’s a handy table that lays out the average costs from some of the most popular insurance companies in Massachusetts. Use this as your cheat sheet when shopping around:
| Insurance Provider | Average Annual Cost |
|---|---|
| Progressive | $1,150 |
| Geico | $1,020 |
| State Farm | $1,260 |
| Allstate | $1,400 |
| Liberty Mutual | $1,350 |
These numbers are averages, which means your actual cost might be less—or more. That’s why it’s crucial to get personalized quotes.
Tips for Selecting an Affordable Auto Insurance Provider
Finding an affordable provider isn’t just about price. You need to consider the coverage and customer service too. Here is the deal:
- Shop around and get quotes from multiple insurers.
- Check for discounts like safe driver or multi-policy.
- Read reviews to see how good their customer service is.
Pro Tip: Always ask about hidden fees and surcharges that might not be included in the initial quote.
By doing a bit of homework, you can snag a policy that doesn’t break the bank and still covers your needs. Remember, cheap is great, but value is even better!
Discounts and Savings Opportunities
Want to slash your auto insurance bill in Massachusetts? You’re not alone. With the right strategies, you can significantly cut down your costs.
Auto insurance in Massachusetts doesn’t have to break the bank. Understanding and leveraging discounts can make a huge difference. But many people overlook these easy savings. Let’s change that.
Strategies for Reducing Auto Insurance Costs
First, maintain a clean driving record. It’s the simplest way to qualify for lower rates. Insurance companies love safe drivers. Also, consider raising your deductible. A higher deductible means lower monthly premiums. But remember, you’ll pay more out-of-pocket if you file a claim.
Pro Tip: Install anti-theft devices and report them to your insurer. It’s an easy way to snag a discount.
Common Discounts Offered by Insurance Companies
Take advantage of these common discounts that most insurers offer:
- Multi-policy Discount: Bundle home and auto insurance.
- Good Student Discount: Available for students maintaining a high GPA.
- Safe Driver Discount: For those with no accidents or tickets.
- Low Mileage Discount: If you drive less than the average driver.
- Payment Discounts: Pay upfront or set up automatic payments.
These discounts can stack up, saving you hundreds annually. Always ask your insurer which ones you qualify for.
Bundling Policies to Save on Premiums
Combining different types of insurance policies is a great way to lower your rates. Known as bundling, it offers significant savings. By insuring your home, auto, and even life insurance with the same provider, you can unlock discounts that you wouldn’t get otherwise.
Here’s the deal: Bundling might not always be cheaper, so compare quotes from different insurers first. But when it works, it really works. Step #1, list out all your insurance needs. Step #2, ask your provider about bundling options. Step #3, enjoy the savings.
Impact of Driving Records on Insurance Rates
Did you know that a single speeding ticket can jack up your insurance rates by a whopping 20%? That’s right. Your driving record plays a crucial role in determining how much you fork out for auto insurance in Massachusetts.
Insurance companies see your driving history as a crystal ball. A clean slate tells them you’re a safe bet, while a tarnished record makes them think you’re risky. This risk assessment directly impacts the premium you pay.
Influence of a Clean Driving Record on Premiums
A spotless driving record is like a golden ticket. It screams “low risk” to insurers. Keeping your record clean can help you score some of the lowest premiums available. How? Insurance companies often reward cautious drivers with significant discounts.
The key is to practice defensive driving. Safe drivers are less likely to file claims, and that’s music to any insurer’s ears. Plus, some companies offer ‘Good Driver Discounts’ as a little thank you for staying out of trouble.
Consequences of Traffic Violations on Costs
But what if you’ve racked up a few tickets? Brace yourself. Traffic violations can leave your wallet hurting. Insurers don’t take kindly to risky behavior, and even minor offenses can boost your rates.
Major infractions like DUI or reckless driving? Those can cause your premiums to skyrocket. We’re talking increases of 50% or more in some cases. Yikes!
Maintaining a Good Driving Record
Here’s the deal: keeping a pristine driving record can save you big time. So how do you ensure it stays clean?
- Always obey traffic signals and speed limits.
- Consider taking a defensive driving course. Some insurers might even give you a discount for it.
- Avoid distractions like texting while driving.
Pro Tip: Check with your insurance provider to see if they offer a “safe driver” program or app. It can track your habits and potentially lower your rates.
Remember, a little caution goes a long way in keeping both your driving record and insurance rates in good shape.
Future Trends in Auto Insurance
Ever wonder how much auto insurance costs will rise in the next few years? You’re not alone. But here’s the kicker: prices might not just increase—they could transform completely.
Massachusetts is at the forefront of some major shifts in the auto insurance landscape. As technology evolves and regulations adapt, we’re about to see some exciting changes that could significantly impact your wallet and safety on the road. Here is the deal: understanding these trends now could save you a lot of money down the line.
Predicting Changes in Auto Insurance Pricing Trends
Auto insurance pricing is a moving target. One day it’s up, the next it’s down. BUT what if I told you that the way insurers calculate your premium could be turned upside down? Thanks to big data and AI, insurers are getting smarter about risk assessment, leading to more personalized pricing. This means if you’re a safe driver, you might pay far less than someone with a riskier profile.
Technological Advancements Shaping the Industry
Technology is not just changing how we drive; it’s revolutionizing how we’re insured. Telematics devices are being installed in more vehicles, providing insurers with real-time data on driving behavior. It’s like having a personal driving coach in your car. This data can lead to lower premiums for responsible drivers, but it also means less privacy.
Pro Tip: Install a telematics device for a chance at significant discounts. Insurers love data from these gadgets.
Future Scenarios for Auto Insurance Regulations in Massachusetts
Regulations aren’t just hurdles—they’re protectors. But what happens when they evolve? In Massachusetts, we might see stricter rules around data privacy due to the influx of personal data from new tech. This could mean better protection for you, but also potential changes in how rates are determined. Keep an eye on legislative updates to stay ahead.
Final Thoughts
Wrapping it all up, understanding auto insurance in Massachusetts is more than just knowing the numbers. It’s about leveraging every opportunity to save while ensuring comprehensive coverage. With the right knowledge and strategies, you can confidently navigate your options and hit the road with peace of mind. Drive safe and save smart!
Answers to Common Questions
What are the minimum auto insurance coverage requirements in Massachusetts?
The state mandates coverage including bodily injury to others, personal injury protection, bodily injury caused by an uninsured auto, and damage to someone else’s property.
How does age affect auto insurance costs in Massachusetts?
Generally, younger drivers tend to pay higher premiums due to their lack of experience, while older, more experienced drivers often benefit from lower rates.
Can my driving record impact my insurance rates?
Absolutely! A clean driving record can lower your premiums, while traffic violations and accidents can lead to higher insurance costs.
Are there discounts available to reduce auto insurance costs in Massachusetts?
Yes, many insurers offer discounts for things like bundling policies, having a good driving record, and even for being a student with good grades.
What impact does the type of vehicle have on insurance rates?
Luxury cars and sports vehicles often come with higher insurance rates due to their expensive repair costs and increased risk of theft.
How can I choose an affordable auto insurance provider?
Compare quotes from multiple insurers, consider customer reviews, and take advantage of available discounts to find the best value.
